

UK real GDP grew by 0.4% in Q2 2026, demonstrating resilience against downside risks from the ongoing conflict in Iran. Consumer-facing services in particular showed an uptick towards the end of the quarter, driven by the World Cup and the record-breaking summer heat. After a stronger than anticipated first half of 2026, Cebr expects this resilience to taper, with growth coming in at 1.2% for the year.
Weakness in the UK’s labour market has persisted, with job vacancies and earnings growth falling to multi-year lows. Labour demand has remained stubbornly depressed, driven by elevated economic uncertainty, new cost pressures, and technological disruption. These forces are expected to keep unemployment elevated through the second half of 2026.
Headline CPI inflation eased to 2.8% in Q2 2026, as a lower Ofgem price cap and weak labour market tempered inflationary pressures from the Iran conflict. That said, inflation came in significantly above pre-war forecasts and has accelerated to 2.9% in July following the introduction of a higher energy price cap for Q3. Cebr expects CPI inflation to average 3.1% in 2026.
While growth surprised to the upside in the Eurozone in Q2, it disappointed in the United States. The central challenge to the outlook remains Iran-related inflation. The European Central Bank has already acted to raise interest rates, while recent communications from the Federal Reserve have been notably hawkish, reintroducing the possibility of a rate hike before the end of the year. China experienced a notable growth slowdown in Q2, with disruptions stemming from the Middle East weighing on activity.
London, the North East, and the North West are projected to be the UK’s fastest growing regions in 2026, with the slowest growth rates expected to be shown by the devolved nations and Yorkshire and the Humber.
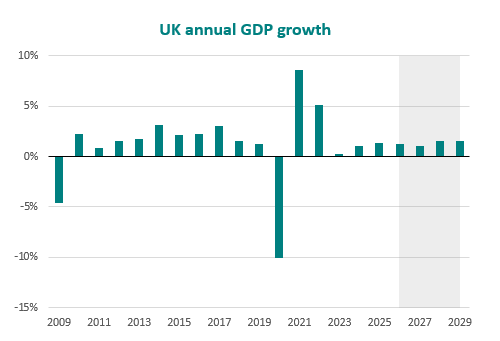
• UK growth prospects
• The labour market
• Inflation and interest rates
• Global growth prospects
• Regional prospects
• Topical economic issues